Philanthropic Tax Strategies
Charitable giving is more than a philanthropic endeavor. It can be a powerful financial planning strategy that helps reduce the tax burden while enhancing overall financial and estate plans. Thoughtful charitable giving, including the timing of contributions and the selection of tax-efficient assets, can enhance both tax advantages and philanthropic impact. This approach can generate meaningful value for charitable causes while supporting long-term financial and estate planning goals.
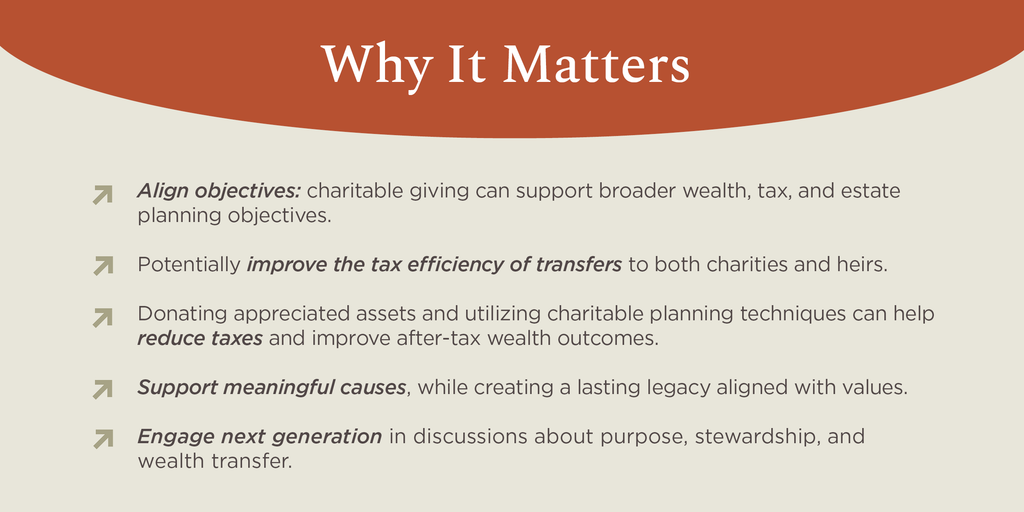
Key Tax Planning Opportunities
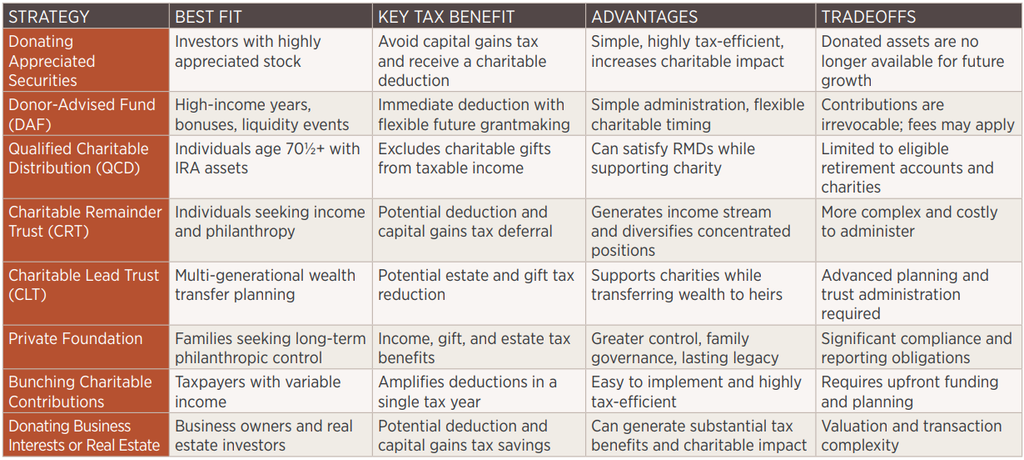
Structured charitable planning can be especially valuable during high-income years, liquidity events, or retirement transitions.
Considerations & Risks
Tax Deduction Limitations:
Charitable deductions may be subject to IRS percentage limitations, carryforward rules, and substantiation requirements, which can reduce the anticipated tax benefit.
Valuation and Documentation Requirements:
Non-cash gifts (i.e., closely held business interests, real estate, or other illiquid assets) may require formal appraisals and additional documentation.
Market and Opportunity Cost:
Donating appreciated assets eliminates future appreciation potential and may impact long-term growth if not incorporated into an overall investment strategy.
Charitable Vehicle Complexity:
DAFs, charitable trusts, and private foundations all offer benefits but may involve administrative responsibilities, costs, and regulatory requirements.
Estate Planning Tradeoffs:
Assets directed to charitable organizations reduce the amount available for heirs, making it important to balance philanthropic and family legacy objectives.
Changing Tax Laws:
Future tax law changes could affect the value of deductions, estate tax planning opportunities, and the overall effectiveness of charitable strategies.
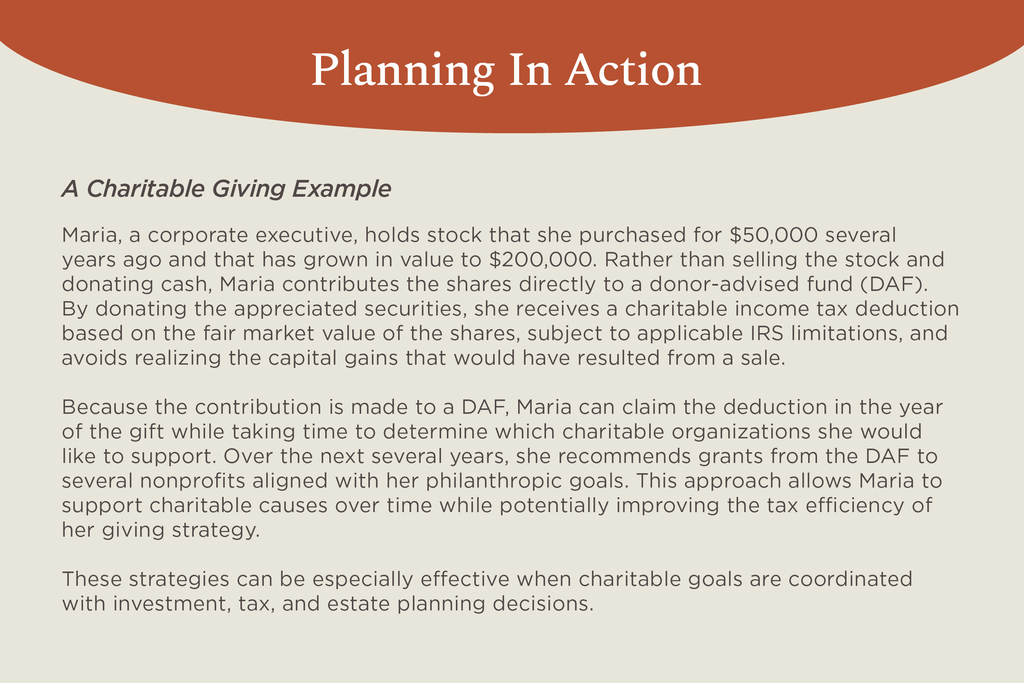
Charitable giving can be a meaningful component of a comprehensive financial plan. Reach out to your financial advisor to discuss how philanthropic strategies may support your long-term wealth, tax, and legacy planning goals.